ReliaFund Blog
ACH Authorization Forms: Free Templates and Requirements for WEB, PPD, CCD, and TEL
Every ACH debit needs the account holder's authorization, and the right form depends on the SEC code. This guide covers Nacha's seven required elements, recurring notices, and retention, with free PPD, WEB, TEL, and CCD templates to adapt.
Read More 
Remote Deposit Capture for Check Cashers and Businesses: A Setup Checklist
Remote deposit capture lets you scan checks where you take them and deposit the images electronically. This checklist covers what banks ask for before approval, scanner choice, controls against duplicate deposits, and how to store and destroy original checks.
Read More 
Writing Your ACH Fraud Monitoring Procedure: A Template for Small Originators
Since June 22, 2026, Nacha's fraud monitoring rule has covered every business that sends ACH payments. This guide explains what the rule requires and what counts as risk-based monitoring, then gives you a fill-in procedure template and review log.
Read More 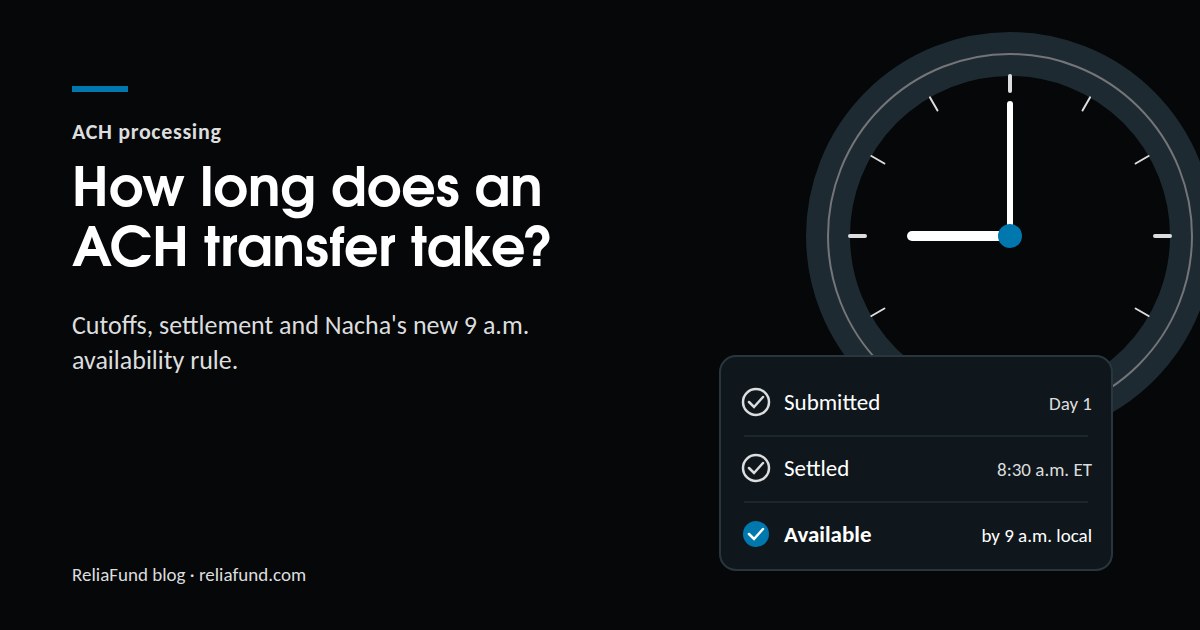
How Long Does an ACH Transfer Take? Settlement, Cutoffs, and the 2026 Funds-Availability Rule
Most ACH transfers settle in one business day, and Same Day ACH settles within hours. This guide covers cutoff times, return windows, and holidays. It also explains Nacha's September 18, 2026 rule: next-day credits must be available by 9 a.m. local time.
Read More 
ACH Fraud Prevention for Businesses: Rules and Controls
ACH fraud prevention is now a written obligation for businesses that send or collect ACH payments. This post covers the 2026 Nacha rule changes, return rates as an early warning, and controls for collections and disbursements. It also covers data security, the Contact Registry, and the annual audit.
Read More 
Level 2 and Level 3 Processing for B2B Merchants in 2026
Businesses that accept corporate or purchasing cards may be paying more interchange than they need to. This post explains Level 2 and Level 3 processing and what changed in 2025 and 2026. It also covers which transactions qualify, typical savings, and why data quality now matters.
Read More 
How to Reduce Chargebacks for Small Businesses: 7 Fixes
A chargeback costs you the sale, a dispute fee, and staff time. This post explains how chargebacks work, which dispute category drives yours, and seven fixes that reduce them. It also covers when to fight or refund and where ACH fits as an alternative.
Read More 
PCI Compliance for Small Businesses: What You Owe
PCI compliance for a small business depends on how much of your business the standard reaches. This post explains what PCI DSS covers, why scope matters, and the tools that shrink it. It also covers choosing the right self-assessment questionnaire and the script requirements.
Read More